Category: Financial Health

  • Reevaluate Your Budget

    FINANCIAL HEALTH

    Women working on a budget.

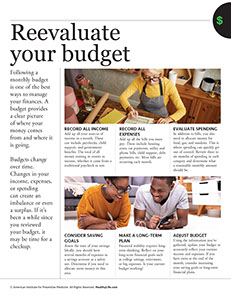
    Following a monthly budget is one of the best ways to manage your finances. A budget provides a clear picture of where your money comes from and where it is going.

    Budgets change over time. Changes in your income, expenses, or spending can create an imbalance or even a surplus. If it’s been a while since you reviewed your budget, it may be time for a checkup.

    Record all income

    Add up all your sources of income in a month. These can include paychecks, child support, and government benefits. The total of all money coming in counts as income, whether it came from a traditional paycheck or not.

    Record all expenses

    Add up all the bills you must pay. These include housing costs, car payments, utility and phone bills, child support, debt payments, etc. Most bills are recurring each month.

    Evaluate spending

    In addition to bills, you also need to allocate money for food, gas, and sundries. This is where spending can quickly get out of control. Review three to six months of spending in each category and determine what a reasonable monthly amount should be.

    Consider saving goals

    Assess the state of your savings. Ideally, you should have several months of expenses in a savings account as a safety net. Determine if you need to allocate more money in this area.

    Make a long-term plan

    Financial stability requires long-term thinking. Reflect on your long-term financial goals such as college savings, retirement, or big expenses. Is your current budget working?

    Adjust budget

    Using the information you’ve gathered, update your budget to accurately reflect your current income and expenses. If you have extra at the end of the month, consider increasing your saving goals or long-term financial plans.
    © American Institute for Preventive Medicine
  • Deal With Debt

    Financial Health

    Get out of debt on your own or with help.

    Whether it’s from living above your means, expensive medical bills, a job loss, or supporting your parents, you can eliminate debt. The first step is to avoid getting deeper in debt. Limit spending to essentials and follow a plan to pay down the debt.

    On your own:

    *  Cut up credit cards or put them away until they are paid off.

    *  Rank order what needs to be paid off – student and other loans, credit cards, etc.

    *  Contact your creditors right away to work out payment plans that you can manage. Do this before debt collectors get involved. If you can’t work out a plan with your mortgage company, contact the local office of the Department of Housing and Urban Development or the housing authority in your state, city, or county for help in finding a legitimate housing counseling agency near you.

    *  Bring in more income from a part time job and selling household items you no longer need at a garage sale or online site, such as Ebay. Consider selling some of your gold and silver jewelry for cash.

    Get professional help from:

    *  A professional financial planner through work

    *  The Financial Planning Association (FPA) at 800.647.6340 orwww.fpanet.org

    *  The National Foundation for Credit Counseling at 800.388.2227 orwww.nfcc.org/FirstStep/firststep_03.cfm.

    Beware of any debt relief service that*:

    *  Charges any fees before it settles your debts

    *  Pressures you to make “voluntary contributions,” another name for fees

    *  Touts a “new government program” to bail out personal credit card debt

    *  Guarantees it can make your debt go away

    *  Tells you it can stop all debt collection calls and lawsuits

    *  Guarantees that your credit card and any other debt not tied to an asset, such as your house, can be paid off for just pennies on the dollar

    *  Offers to enroll you in a debt management program (DMP) without teaching you skills to budget and manage your money

    *  Adapted fromwww.ftc.gov/bcp/edu/pubs/consumer/credit/cre19.shtm

    Action Step

    Pay off the credit card or other debt with the lowest balance first. After this is paid in full, pay down the next debt with the lowest balance.

    Ways to Well-Being book by the American Institute for Preventive Medicine. www.HealthyLife.com. All rights reserved.

    © American Institute for Preventive Medicine
  • Save At The Supermarket

    FINANCIAL HEALTH

    Couple at the grocery store.

    While the cost of food is out of your control, smart shopping habits will help keep your grocery bill more manageable.

    Tips to save on groceries

    Shop with a list

    Grocery stores know just how to tempt you to make impulse purchases. With eye-catching end cap displays and strategically placed snack foods, it’s easy to end up bringing home more than you intended. Instead, make a detailed list before you go and stick to it.

    Check the cabinets

    How many times have you purchased an item only to find you already have it hidden in the back of your pantry? As you make your shopping list, carefully check your current food supply to make sure you really need the ingredients.

    Buy in bulk

    When possible, purchase family-sized or bulk items for your most commonly used ingredients. This works especially well for meats, beans, rice, grains, and pasta. When you get home, promptly freeze or store the extra. You can also join a wholesale club to get better prices on bulk food.

    Eat seasonally

    Fruits and vegetables are cheapest when in season. For example, berries are more expensive in the winter than during peak berry season in the summer. Oranges and other citrus are usually cheapest during the winter months. Opt for in-season produce whenever possible.

    Stock up

    Buy more than one when your favorite foods go on sale. Dry goods generally keep for a long time, and many fresh foods can be frozen for longer storage. Keep in mind that you should only stock up on ingredients you regularly use.

    Low-cost recipes

    How you choose to eat is a major determinant of your food budget. If you like to cook gourmet, you’ll need fancier ingredients that cost more. Instead, find tasty recipes that use inexpensive ingredients. Examples include beans, rice, frozen vegetables, tuna, potatoes, and eggs.

    © American Institute for Preventive Medicine
  • Declare Your Independence From Credit Card Overuse

    Financial Health

    Credit cards fanned out on table.

    *  Limit your number of credit cards.

    *  Use 1 or 2 major credit cards that have low interest rates. Individual store and gas cards have very high interest rates.

    *  Only charge what you can pay in full when you get the bill. Or, aim to keep the balance to less than 25 percent of the total amount you can charge.

    *  Pay with cash. If you are an impulse buyer, leave your credit cards at home when you shop. Avoid or limit shopping online and through TV shopping channels.

    Dos

    *  Make payments on time to avoid late fees and a possible increase in your interest rate.

    *  Make more than the minimum payment.

    Don’ts

    *  Don’t open new credit cards to save 10 or more percent. For each new card you open, your credit score could go down 10 points.

    *  Don’t use your credit cards for cash advances.

    ays to Well-Being book by the American Institute for Preventive Medicine. www.HealthyLife.com. All rights reserved.

    © American Institute for Preventive Medicine
  • Save Money On Prescriptions

    FINANCIAL HEALTH

    Pills dropping into bottle.

    FACT: New drugs are protected by patents. After the patent expires, other companies can make a generic version of the drug.

    Knowing about generic drugs can save you money on prescriptions. Tell your doctor or pharmacist you want a generic drug if possible.

    If your prescription is expensive, speak up. Sometimes there’s an alternative that costs less but is still safe.

    Be wary of places that promise free or cheap prescriptions. It may be a scam. Your doctor or pharmacist can tell you about free or low-cost prescription programs.

    © American Institute for Preventive Medicine
  • Make A Date To Plan Your Estate

    Financial Health

    Prepare for the future well-being of your loved ones.

    If you have a will or other estate plan, great! If you are one of 55-70 percent of adults in the U.S. that do not, put it off no longer. State your wishes, now, to give your family peace of mind instead of reasons for family feuding. When making plans, follow your state’s laws.

    Estate plans include:

    *  A will. This document states who you want your assets and property to be transferred to after you die. It also names person(s) you want to raise your children who are under age 18, (if both parents die). Without a will, probate court can decide how to distribute your estate and name a legal guardian for your children. In your will, you name a person (an executor) to carry out the provisions of the will. You can create a simple will online or with a software program. Examples arewww.usalegalforms.comand Nolo’s Quicken WillMaker® Plus (www.nolo.com). Or, use an attorney, especially if you have a family business, a second marriage, property in more than one state, or your assets are complex.

    *  A trust. This holds your assets for your benefit or that of your spouse or children. You need a lawyer to create a trust.

    *  A revocable living trust. This agreement allows you (the grantor) to transfer ownership of your property in a trust to a trustee (often you and your spouse). The trust is in effect while you are living, if you become mentally disabled, and after you die. You choose beneficiaries to transfer ownership of the trust after you die. Assets in the trust are not subject to probate.

    *  Power of attorney. You sign legal documents to name a person to handle your financial decisions if you are no longer able to do this on your own. Without this, your family may fight over your money and possessions, both in and out of court.

    *  Health Care Advance Directives. You can make your health care wishes known through:

    – A living will. This document states your wishes if you can’t state them yourself and you are dying or have a condition from which you are not expected to survive. A Do Not Resuscitate (DNR) can be included.

    – Durable power of attorney for health care. This document names a person who would state your wishes if you can’t make them yourself. You do not have to be dying or be unconscious to have someone speak on your behalf.

    *  Legal protection for pets. This agreement allows you to name a pet guardian and leave funds to take care of your pets needs.

    *  Social media will. This names someone who will follow your wishes to close out or handle your online content, such as email addresses, social media content, and blogs.

    Once you plan your estate, keep it updated. You may want to make changes if you get married, divorce, remarry, or have a child or grandchild.

    Action Step

    Prepare for estate planning. Start with gathering asset documents and account information. Make an appointment with a lawyer. Or use estate planning software or online resources.

    Ways to Well-Being book by the American Institute for Preventive Medicine. www.HealthyLife.com. All rights reserved.

    © American Institute for Preventive Medicine
  • Save Money On Health Expenses

    FINANCIAL HEALTH

    Image of stethoscope and money on top of paper work.

    Unexpected health care costs can be hard on any budget. To help manage your own health care costs:

    *Get preventive care.Well visits and checkups often cost a lot less than treating a disease or illness. Talk to your doctor and dentist about how often you should be seen, and stick to this schedule.

    *Use generic medicines.Name brand medicines can cost hundreds of dollars more than generic ones. Ask your doctor if a generic medicine is available for your condition. Tell your doctor if you are having trouble paying for medications. Drug makers sometimes offer coupons or savings cards for people who need them.

    *Shop around for your prescriptions.Medicine costs can vary widely among pharmacies. Call pharmacies and ask for the cost of your prescription medicine. Some websites also have prescription medicine costs available for pharmacies in your area. You may also wish to look into mail-order pharmacies.

    *Check your medical bills.Make sure there are no mistakes on your doctor, hospital or prescription bills. And, be sure your insurance covered services it is supposed to cover. If you have questions, or think you may be over-billed, call the number listed on your bill.

    Source: Consumer Federation of America

    Watch those late fees!

    A few dollars here, 20 dollars there… late fees can add up. Whether it’s your credit card bill or a service you received, make an effort to pay your bill on time. Avoid late fees by getting bills set up on automatic payment plans. Or, have a special slot on the wall to place bills that haven’t been paid. Then, they won’t get buried under junk mail or other papers on your desk.

    © American Institute for Preventive Medicine
  • An Annual Financial Review

    FINANCIAL HEALTH

    Women writing on paper with laptop next to her.

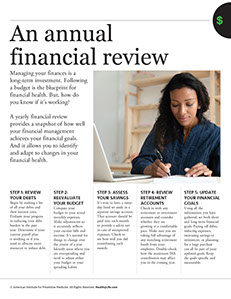
    Managing your finances is a long-term investment. Following a budget is the blueprint for financial health. But, how do you know if it’s working?

    A yearly financial review provides a snapshot of how well your financial management achieves your financial goals. And it allows you to identify and adapt to changes in your financial health.

    Step 1: Review your debts

    Begin by making a list of all your debts and their interest rates. Evaluate your progress in reducing your debt burden in the past year. Determine if your current payoff plan is working or if you need to allocate more resources to reduce debt.

    Step 2: Reevaluate your budget

    Compare your budget to your actual monthly expenses. Make adjustments so it accurately reflects your current bills and income. It’s normal for things to change over the course of a year. Identify areas where you are overspending and need to adjust either your budget or your spending habits.

    Step 3: Assess your savings

    It’s wise to have a rainy-day fund set aside in a separate savings account. That account should be paid into each month to provide a safety net in case of unexpected expenses. Check to see how well you did contributing each month.

    Step 4: Review retirement accounts

    Check in with any retirement or investment accounts and consider whether they are growing at a comfortable pace. Make sure you are taking full advantage of any matching retirement funds from your employer. Double-check how the maximum IRA contribution may affect you in the coming year.

    Step 5: Update your financial goals

    Using all the information you have gathered, set both short and long-term financial goals. Paying off debts, reducing expenses, increasing savings or retirement, or planning for a large purchase can all be part of your updated goals. Keep the goals specific and measurable.

    © American Institute for Preventive Medicine
  • 4 Behaviors For A Healthy Wallet

    FINANCIAL HEALTH

    Concept image of growing leaf with stacked coins.

    1. Make a budget and stick to it.

    Many money experts will tell you that you need to know where your money is going each month. Creating a budget helps to see how much you spend on certain things and where you can cut back to save even more.

    2. Check your credit report each year.

    You are entitled to a free credit report once per year. This is an important step to help spot identity theft early. Your credit report can affect your mortgage rate and ability to get a loan.

    3. Shop around for a good APR on your next loan.

    The annual percentage rate (APR) on a loan is an important number. This is the total cost, including fees and interest, described as a yearly rate. The APR can vary widely between banks or lenders. It pays to take some extra time to find the best rate. Make sure you understand exactly what you will pay.

    4. Put money away for an emergency fund.

    Having an emergency fund offers peace of mind and protection from unexpected costs. Even a few dollars a week can add up, so save what you can.

    Paycheck checkup

    The Internal Revenue Service (IRS) says employees should look at their paycheck withholdings each year. Withholdings are taxes that are taken out of your paycheck.

    It’s especially important to check your withholdings in 2018, the IRS says. The Tax Cuts and Jobs Act, signed in December 2017, may change how much you want withheld.

    The IRS has a withholding calculator on their website at:apps.irs.gov/app/withholdingcalculator. This calculator can help you be sure that you aren’t having too much or too little tax withheld from your paychecks.

    © American Institute for Preventive Medicine

  • Save More, Spend Less

    FINANCIAL HEALTH

    Image of women at kitchen counter with groceries and placing money in a piggy bank.

    According to the American Psychological Association, finances are the number one cause of stress in America. Whether it’s meeting the monthly bills or trying to build a retirement fund, financial worries can be difficult to deal with.

    If you’re looking for ways to stretch your monthly budget, the Federal Trade Commission offers some tips that may help you save more and spend less without feeling the pinch.

    Start with a budget.

    This may not be fun, but it doesn’t have to be long and difficult. You can use something as simple as a two-column sheet of paper. In one column, write your net income for the month. In the other column, record all your expenses: basic monthly bills (mortgage, food, transportation), lifestyle choices (entertainment, eating out, personal care, pets), and other expenses. This will give you a clear idea of how much you need to save or cut back on spending. The FTC website offers a free budget worksheet atwww.consumer.ftc.gov/articles/pdf-1020-make-budget-worksheet.pdf.

    Consider direct deposits into savings accounts.

    Have part of your paycheck go directly into a 401 savings or other type of retirement account. Have additional money put into another savings account for an emergency fund and major expenses as needed.

    Pack lunches.

    A daily $6 spent on lunch adds up to $800 a year. Instead, make extra food for dinner and take leftovers or make your own sandwich. Or, purchase healthy frozen meals when they’re on sale.

    Use free community services.

    Most cities have well-stocked libraries that have books, magazines, music, games, and movies. You can check these items out for free.

    Know that every little bit helps.

    Make small, manageable goals to help you save. Even just $1,000 less on your credit card bill could save you hundreds of dollars in interest each year. Eating out one fewer time each week adds up to big savings in a few months. Rather than being discouraged by a goal that seems impossible, look for small, doable ways to save a few dollars here and there.

    © American Institute for Preventive Medicine